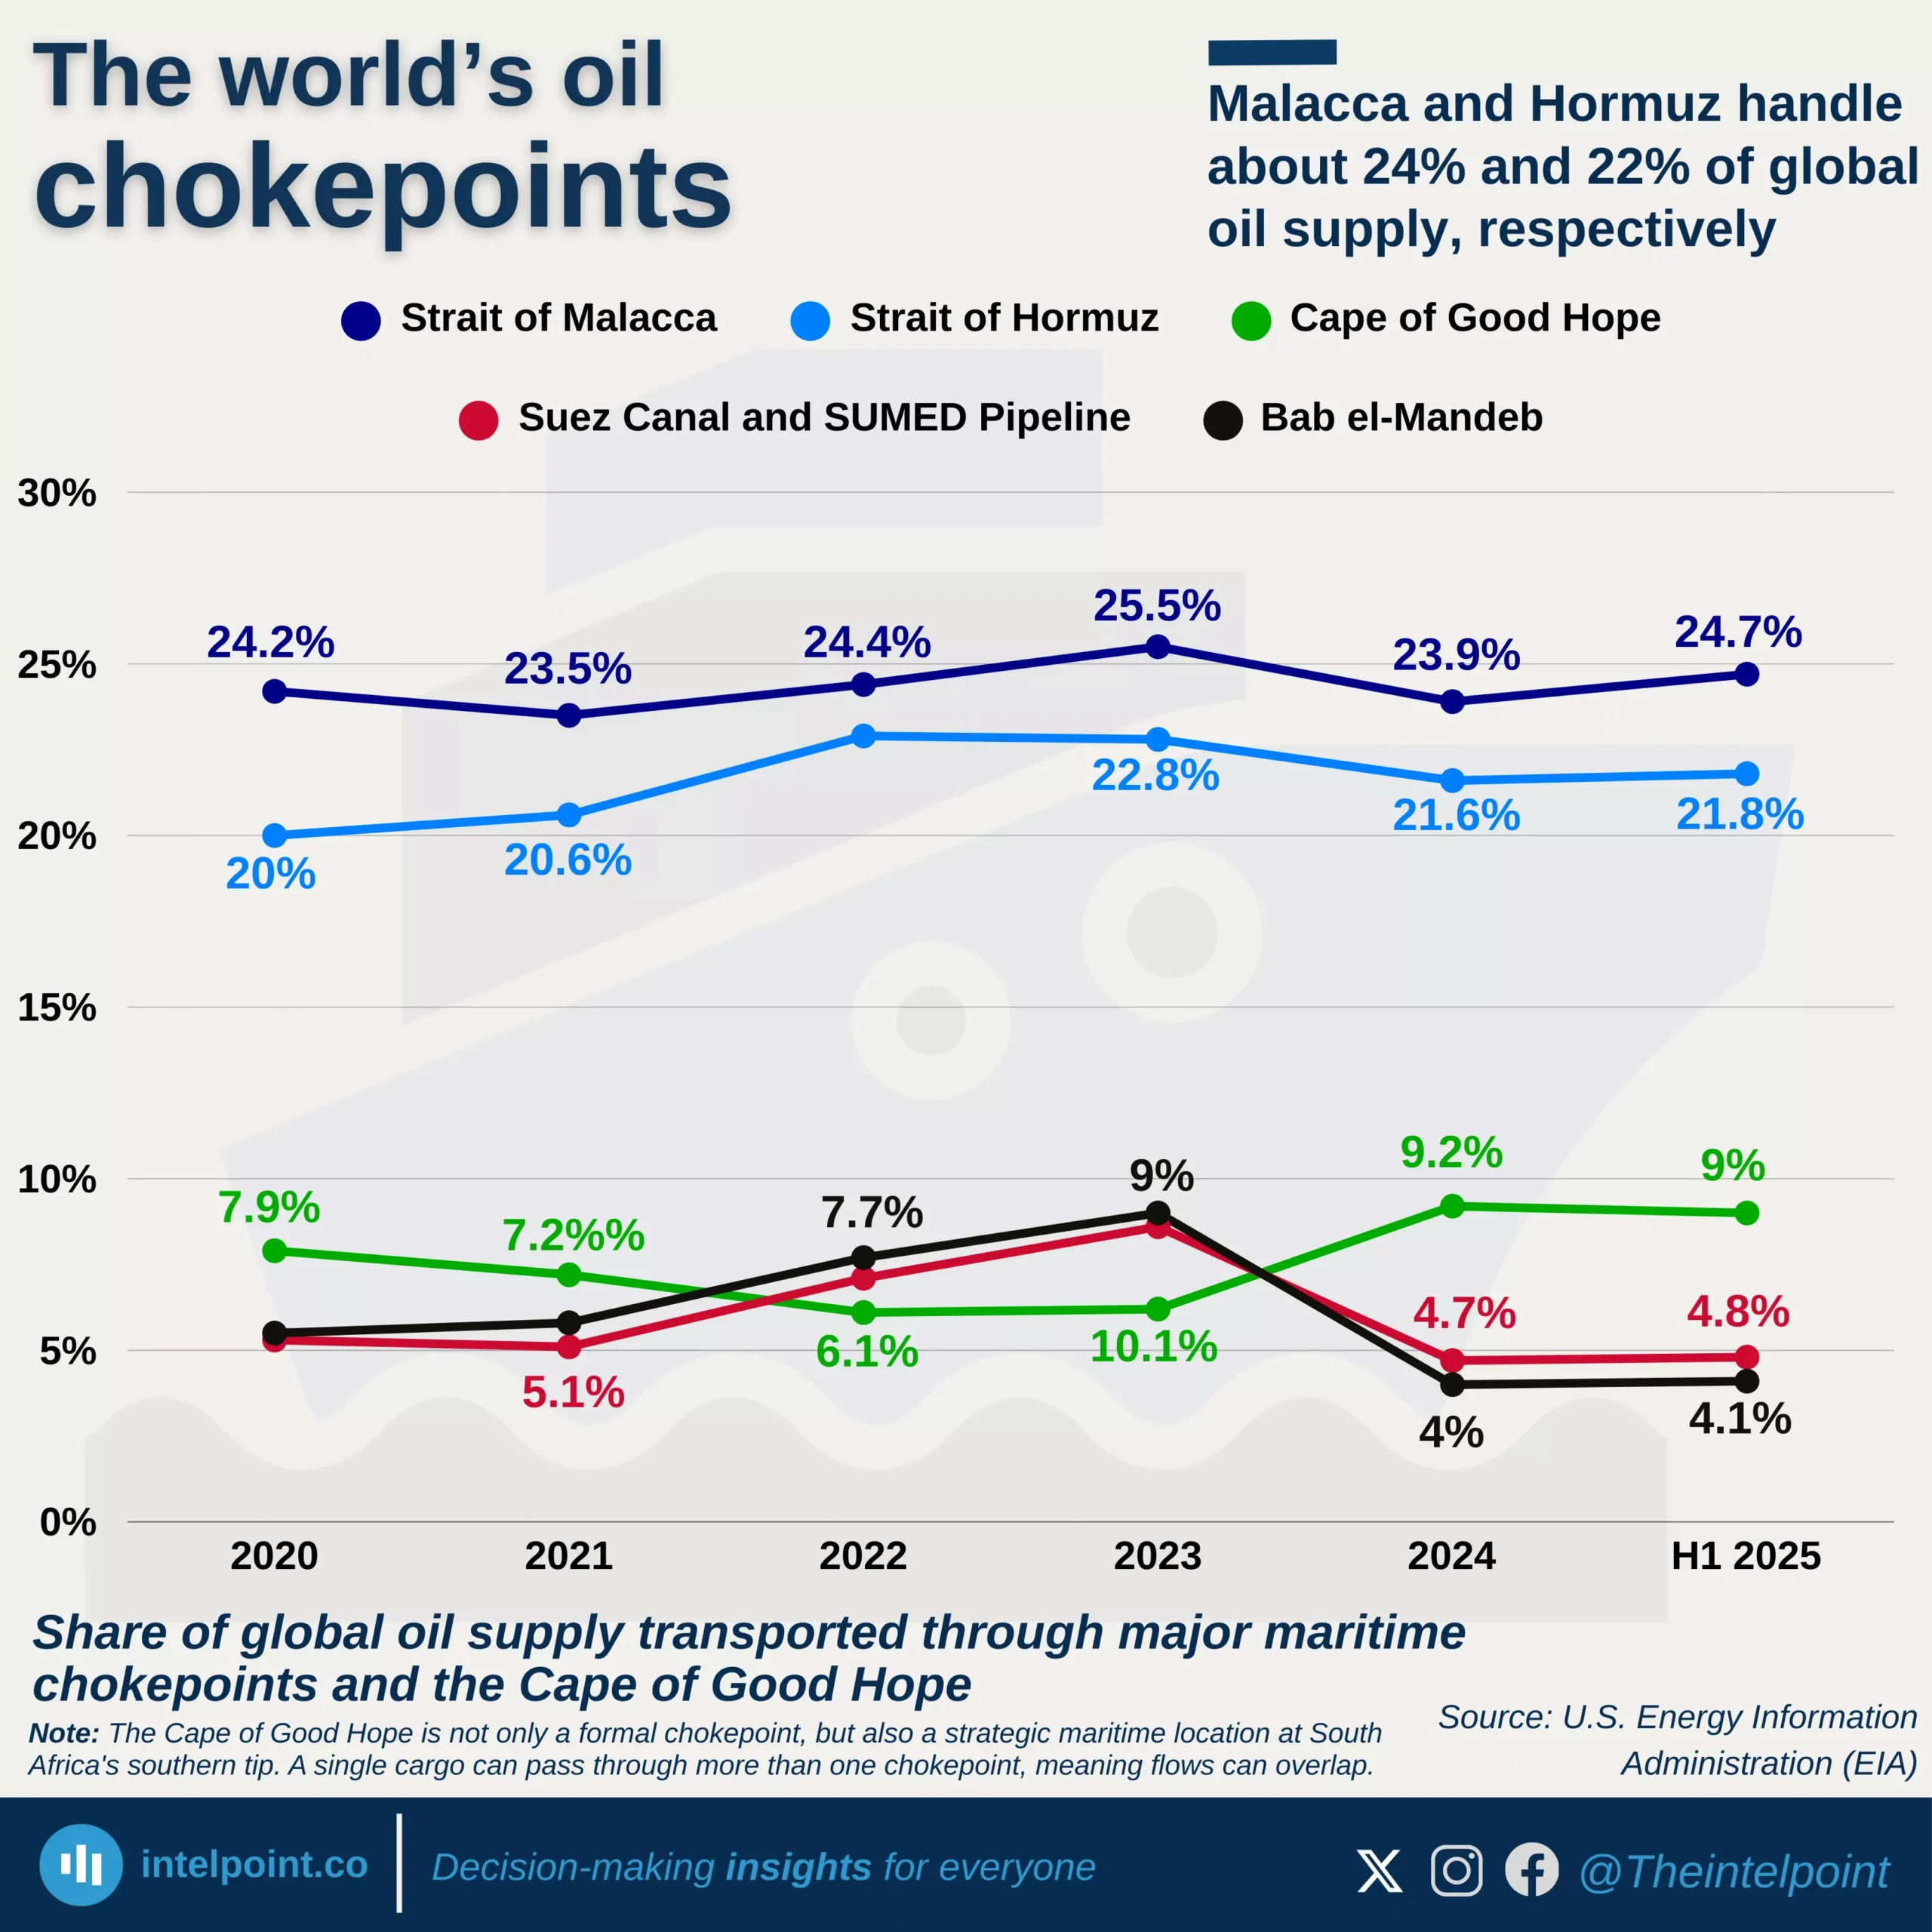
Malacca and Hormuz handle about 24% and 22% of global oil supply, respectively

  • The Strait of Malacca is the world’s most important oil chokepoint, carrying about 24–25% of global oil supply in recent years.
  • The Strait of Hormuz moves around 20–23% of global oil supply, making it the second-largest energy transit chokepoint.
  • The Cape of Good Hope carries about 9–10% of global oil flows, and its share tends to increase when other chokepoints face disruptions.
  • The Bab el-Mandeb saw a sharp drop in oil flow share from about 9% in 2023 to around 4% in 2024, reflecting security concerns affecting shipping in the Red Sea corridor.
  • Oil transported through the Suez Canal and the SUMED pipeline system dropped significantly after 2023, falling from about 8.6% to below 5%, showing how quickly routes shift during geopolitical tensions.
  • The Strait of Malacca’s share has remained consistently high and stable, indicating its structural importance to Asian energy demand.
  • Alternative routes like the Cape of Good Hope in South Africa are longer but strategically crucial, especially when Middle Eastern chokepoints become unstable.

News that the Strait of Hormuz has been blocked by Iran immediately sends shockwaves through global energy markets. The reason becomes clearer when you look at how global oil actually moves. Roughly one-fifth of the world’s oil supply passes through this narrow waterway, making it one of the most critical energy arteries on the planet. When a route carrying that much supply is disrupted, the world has to quickly search for alternatives, and that’s where routes like the Cape of Good Hope suddenly become very important.

When one node becomes unstable, traffic often shifts elsewhere, which explains why alternative passages outside conflict zones can suddenly see increased usage. The Cape of Good Hope offers one such detour. Unlike the Middle Eastern chokepoints currently affected by tensions linked to the Iran–US/Israel conflict and broader regional instability, this route bypasses the entire region. The trade-off, however, is distance. Tankers must travel thousands of extra kilometres around southern Africa, raising shipping costs and delivery times. But when strategic waterways face disruptions, reliability often matters more than speed.
Source:

U.S. Energy Information Administration (EIA)

Period:

2020-2025
HTML code to embed chart
Want a bespoke report?
Reach out
Tags
Related Insights

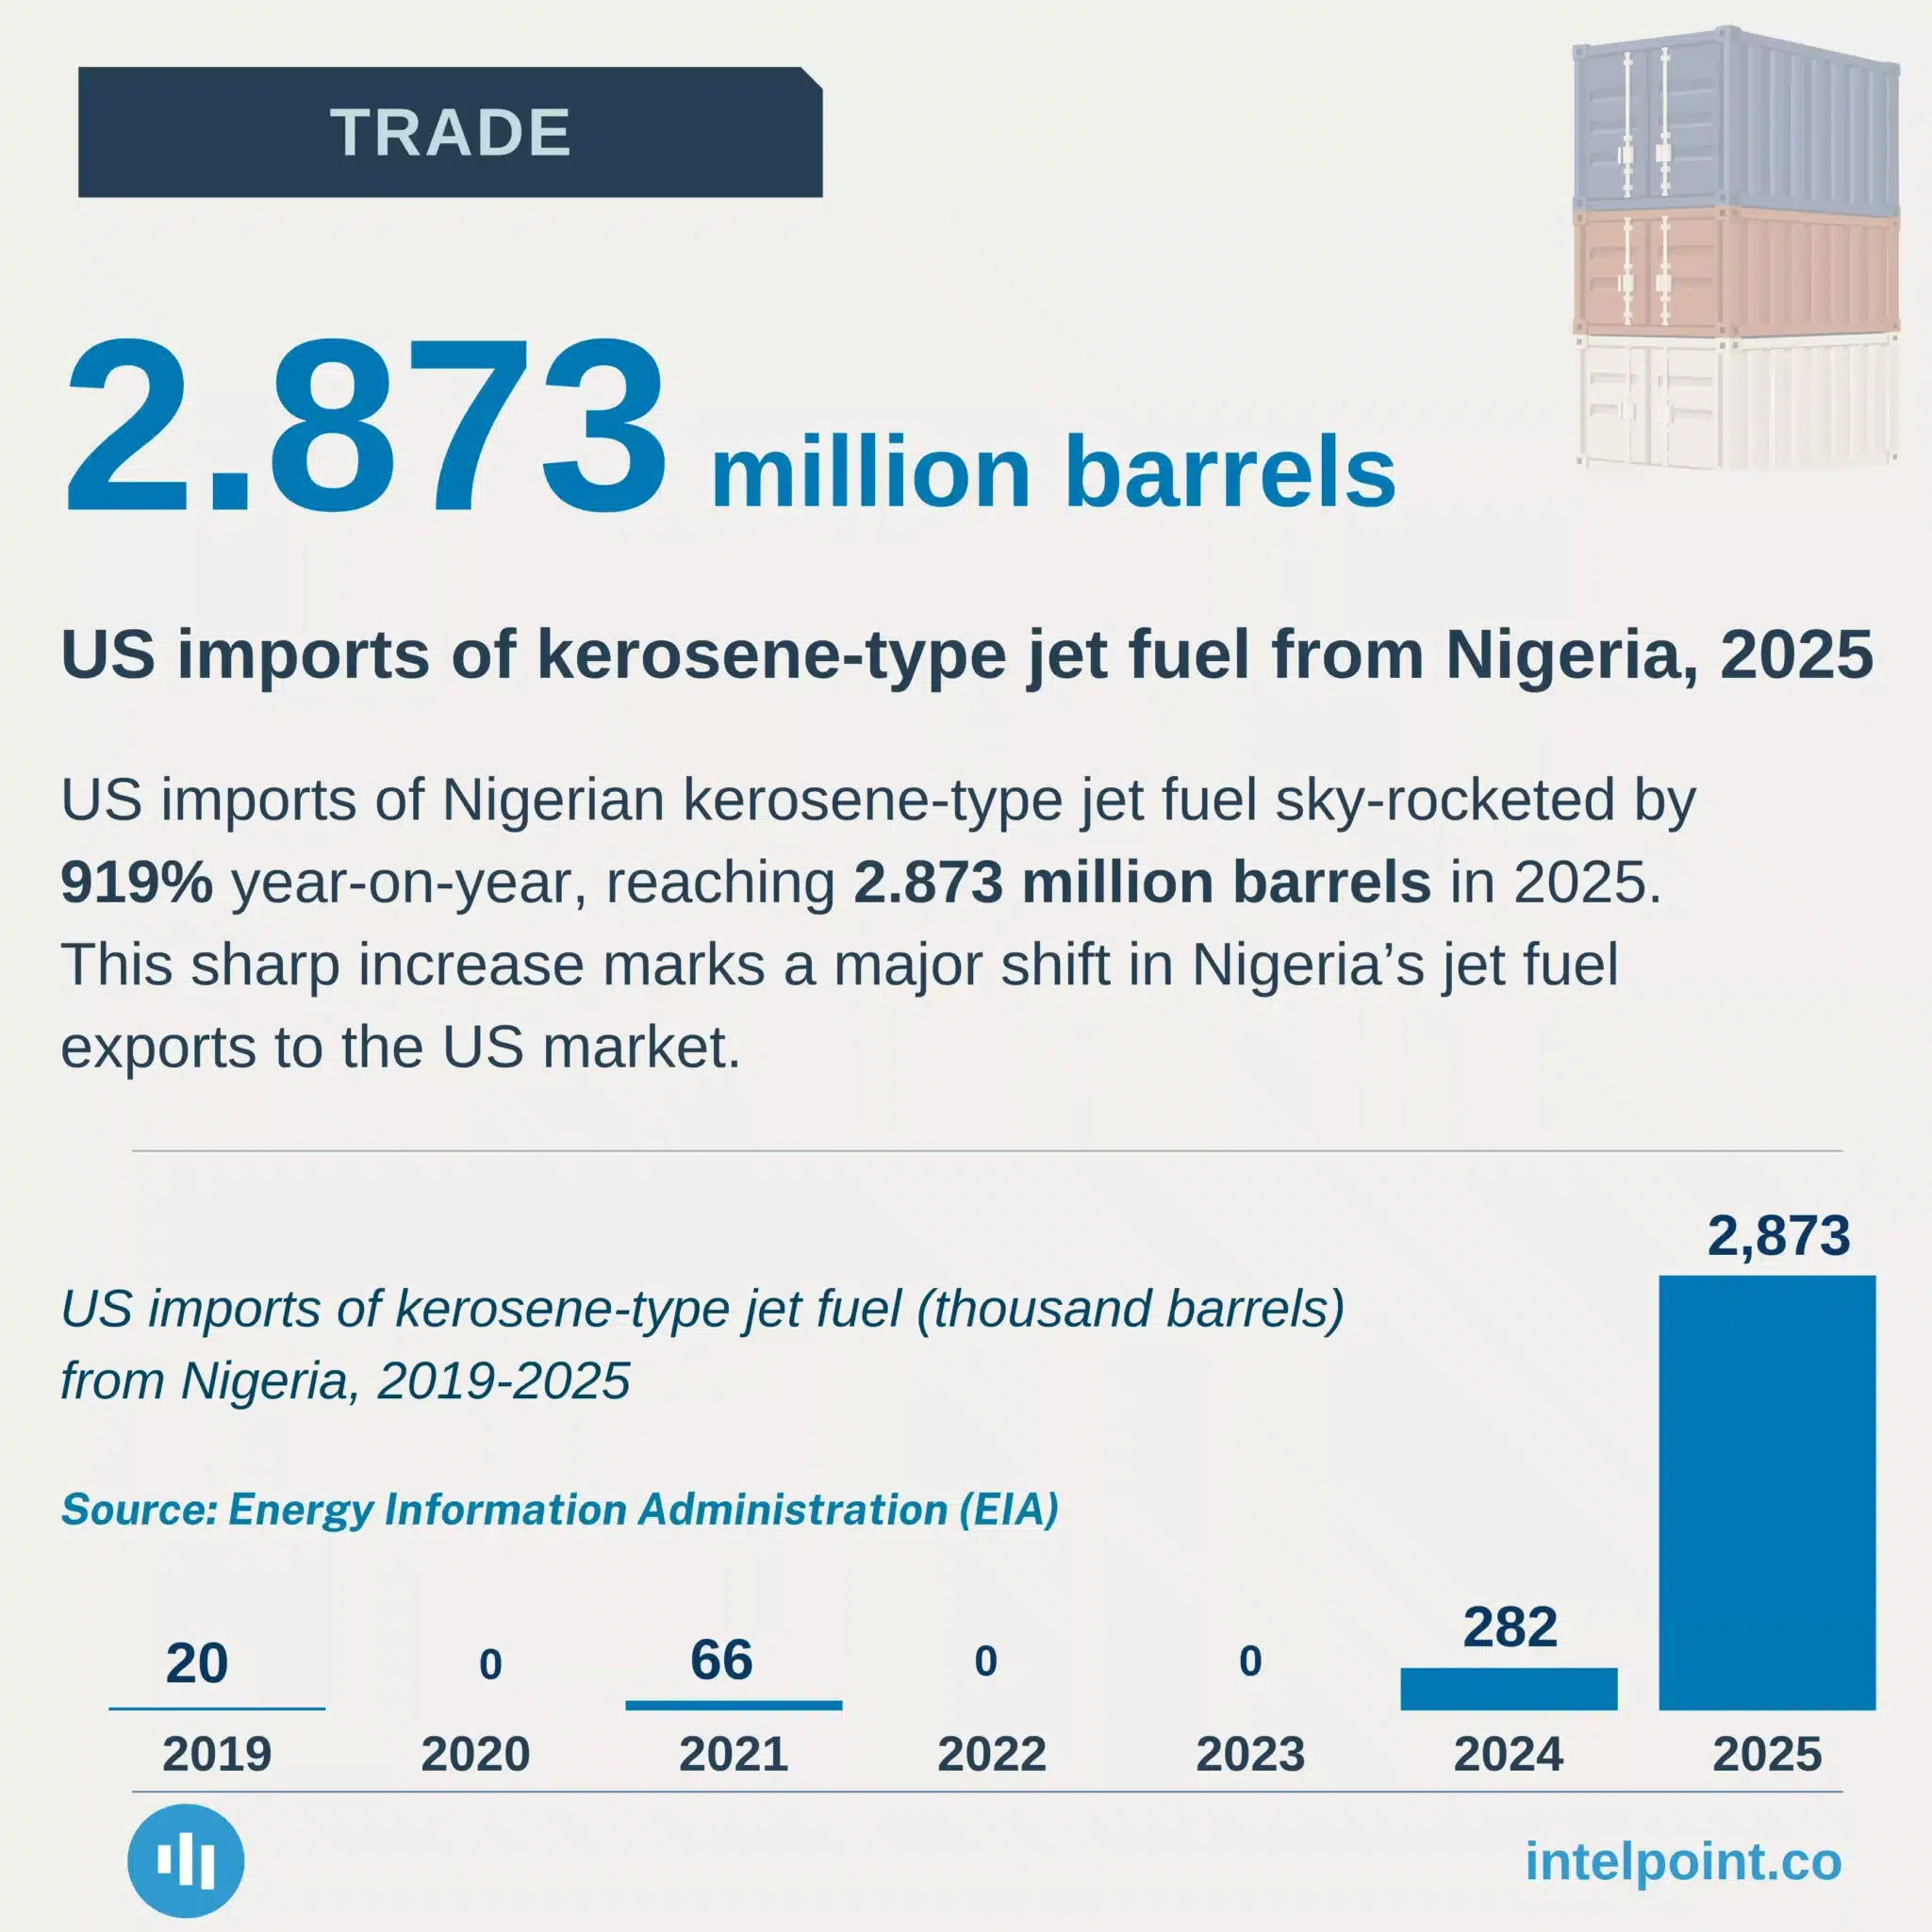
US imports of Nigerian kerosene-type jet fuel sky-rocketed by 919% year-on-year
  • Nigerian jet fuel exports to the U.S. jumped 10-fold to 2.87 million barrels in 2025.
  • Just 86,000 barrels were imported across the U.S. from Nigeria between 1993 and 2023.
  • The 2025 surge was concentrated in five months, amid East Coast refinery disruptions.
  • No Nigerian jet fuel imports were recorded through August 2026, suggesting the surge was temporary.

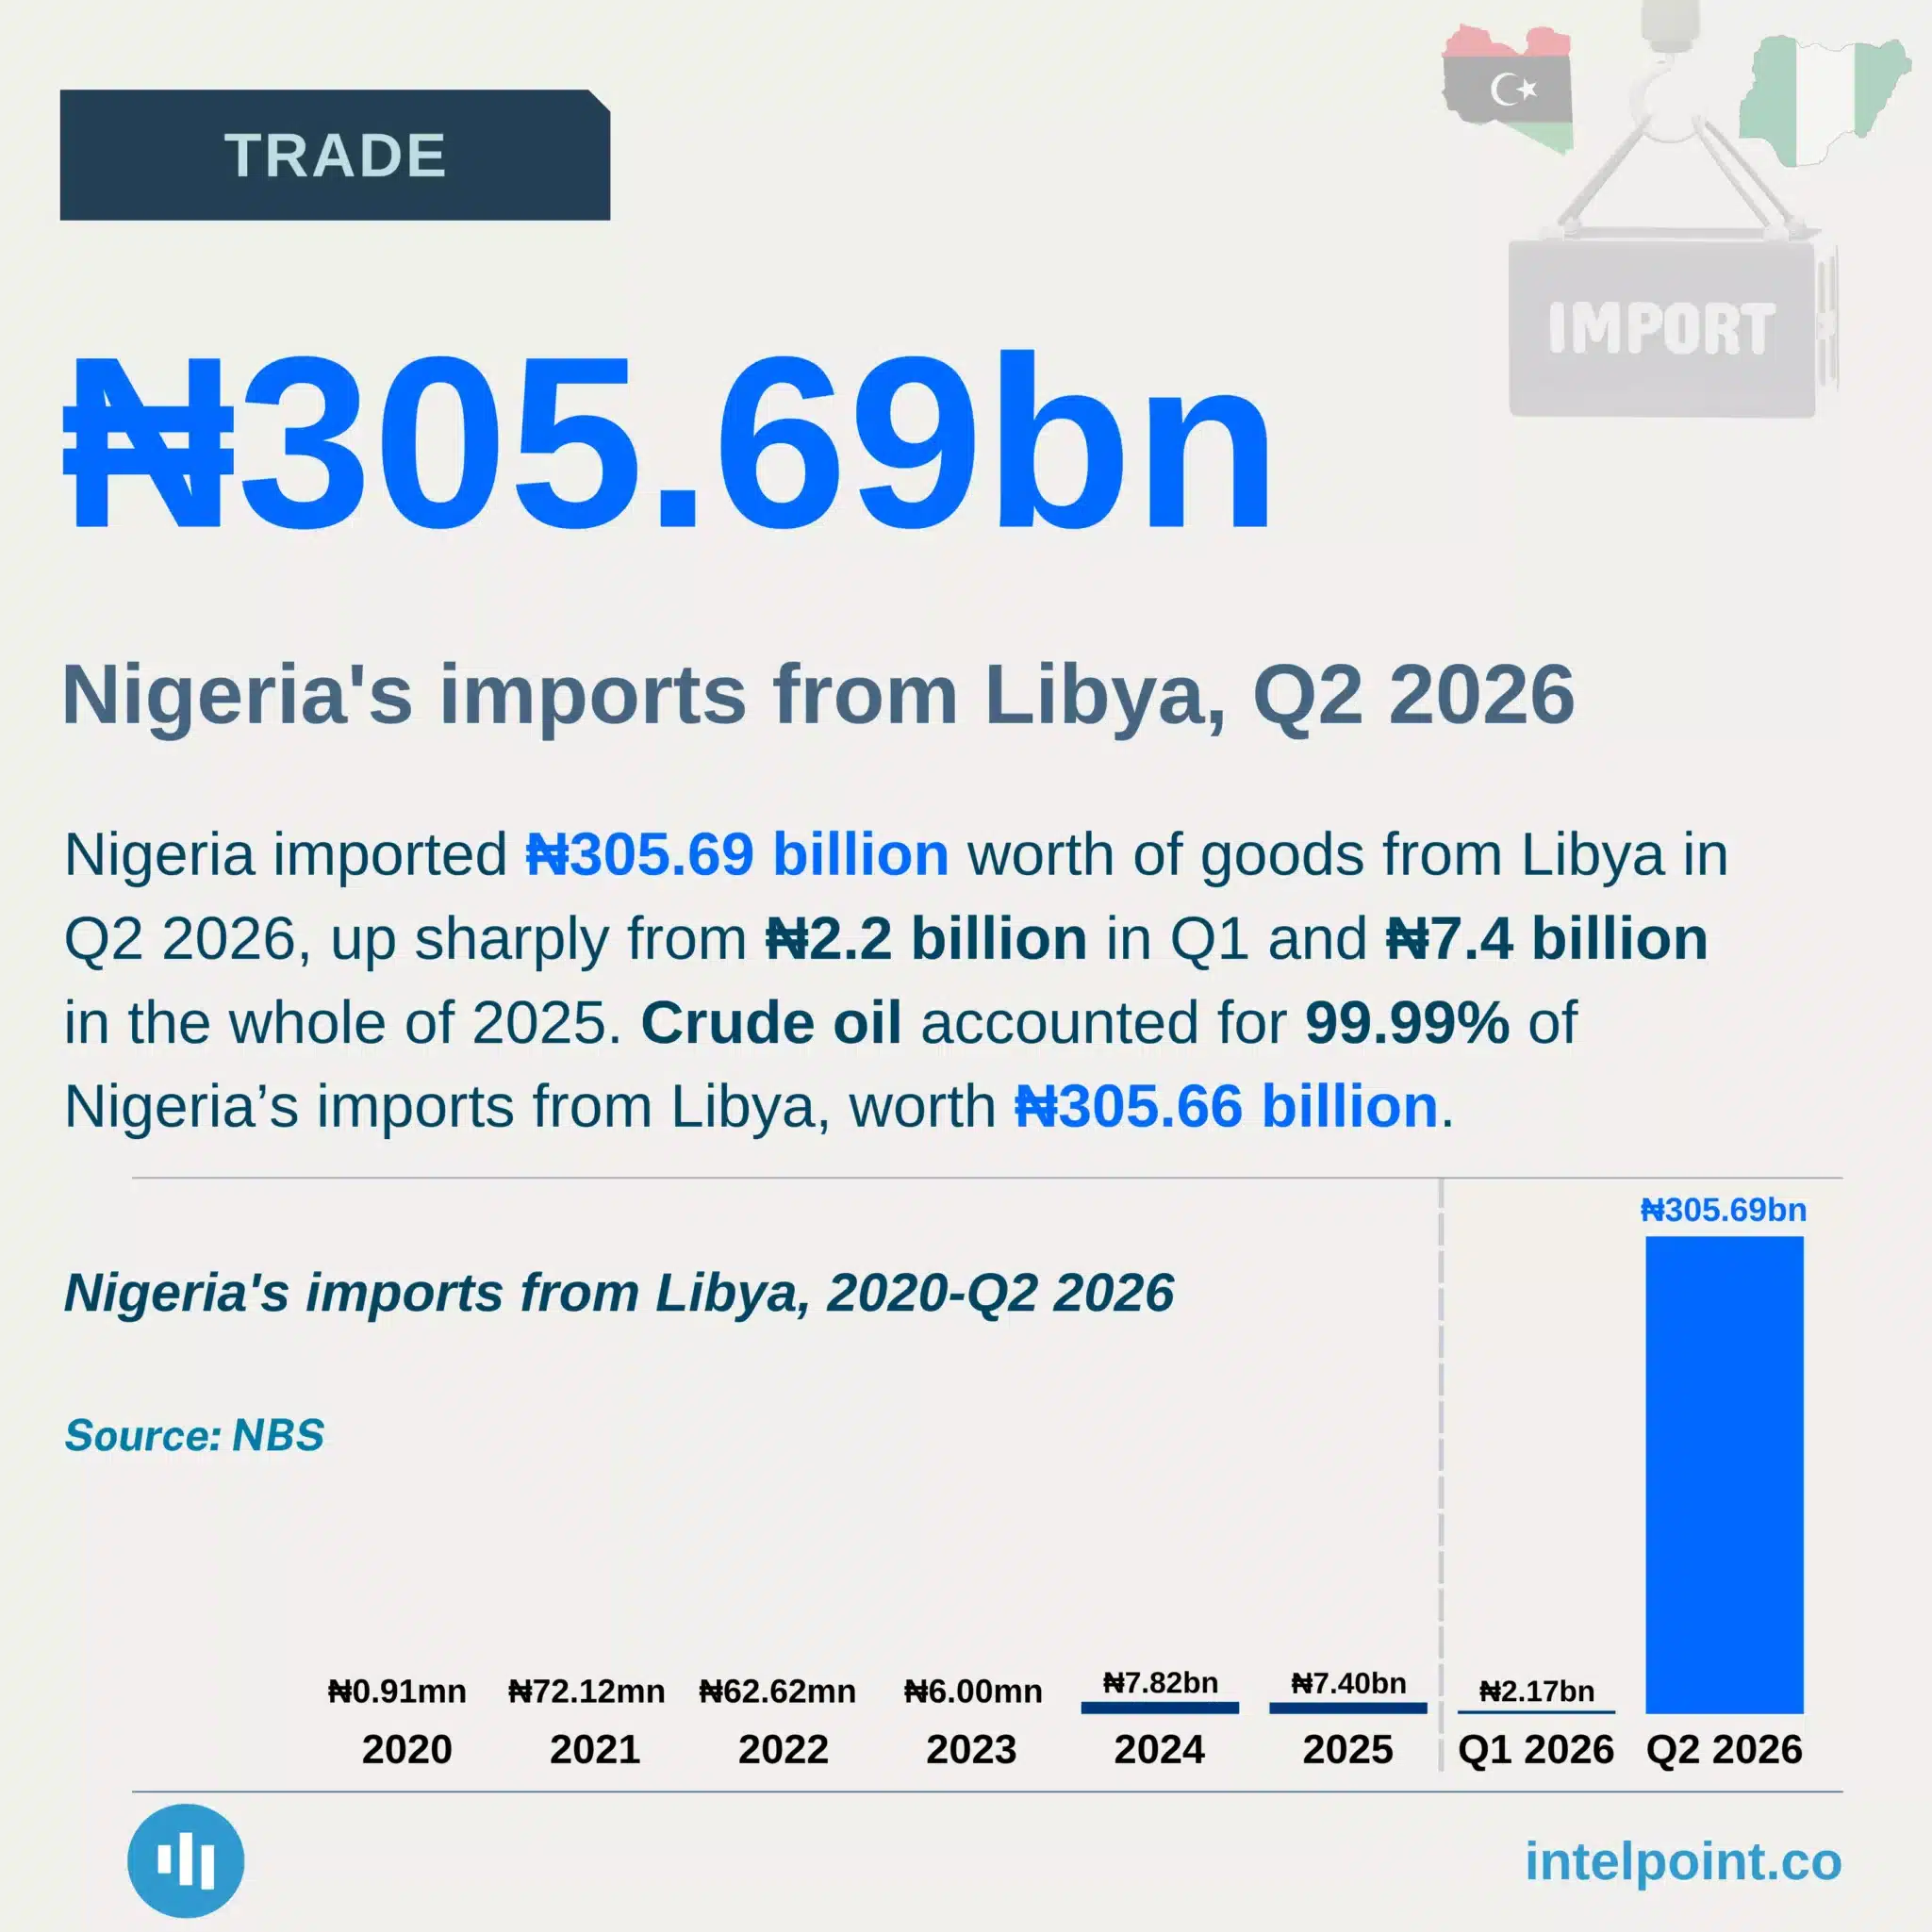
Nigeria bought ₦305.66 billion worth of crude oil from Libya in Q2 2026
  • Nigeria imported ₦305.69bn from Libya in Q2 2026, up from ₦2.17bn in Q1.
  • Crude oil accounted for 99.99% of Q2 imports, worth ₦305.66bn.
  • Libya’s Q2 exports to Nigeria surged from ₦7.4bn in 2025 to ₦305.69bn.
  • Libya became Nigeria’s ninth-largest import source, accounting for 2.12% of total imports in Q2.
  • Nigeria’s imports from Libya were previously dominated by much smaller values, with crude oil driving the sharp 2026 increase.

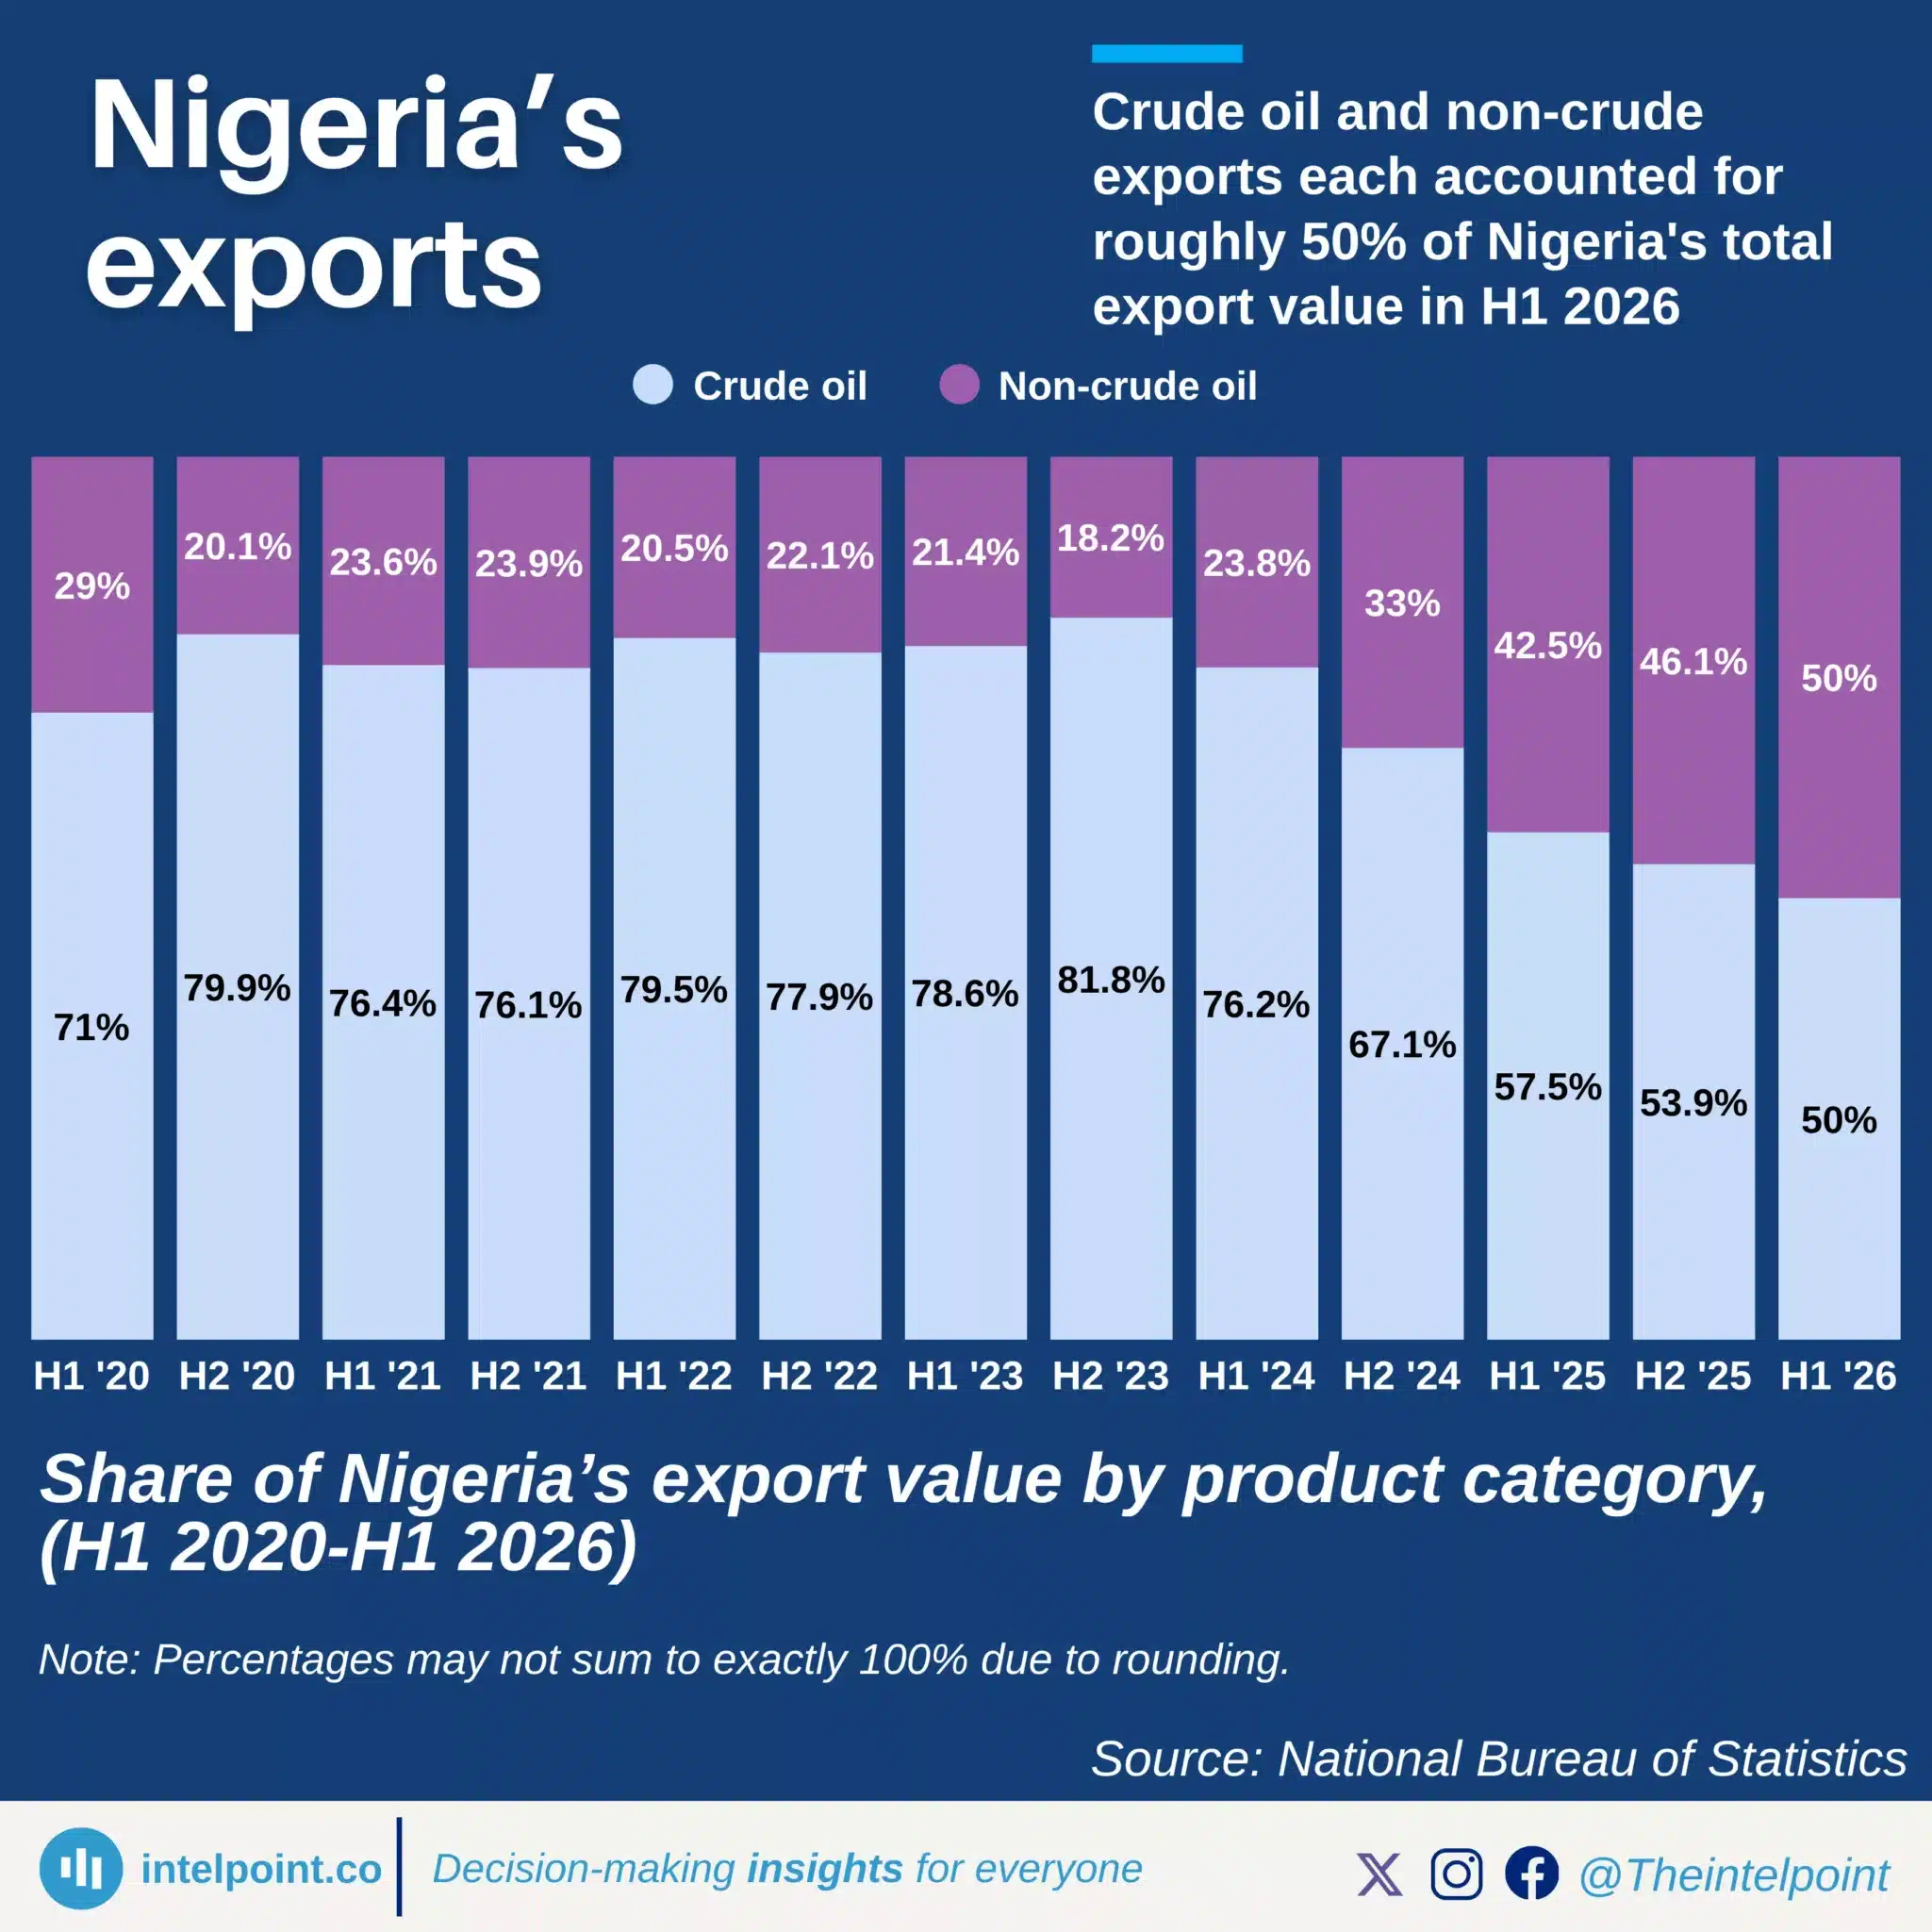
Crude oil and non-crude exports each accounted for roughly 50% of Nigeria's total export value in H1 2026
  • Nigeria’s crude and non-crude exports were nearly equal in H1 2026, at ₦24.1tn and ₦24tn, respectively.
  • Non-crude exports overtook crude in Q2 for the first time in at least six years, reaching ₦14.11tn.
  • Petroleum products and natural gas dominate non-crude exports, while non-oil exports accounted for just 13.8% of Q2 exports.
  • Nigeria’s export mix is shifting, but remains heavily dependent on hydrocarbons.

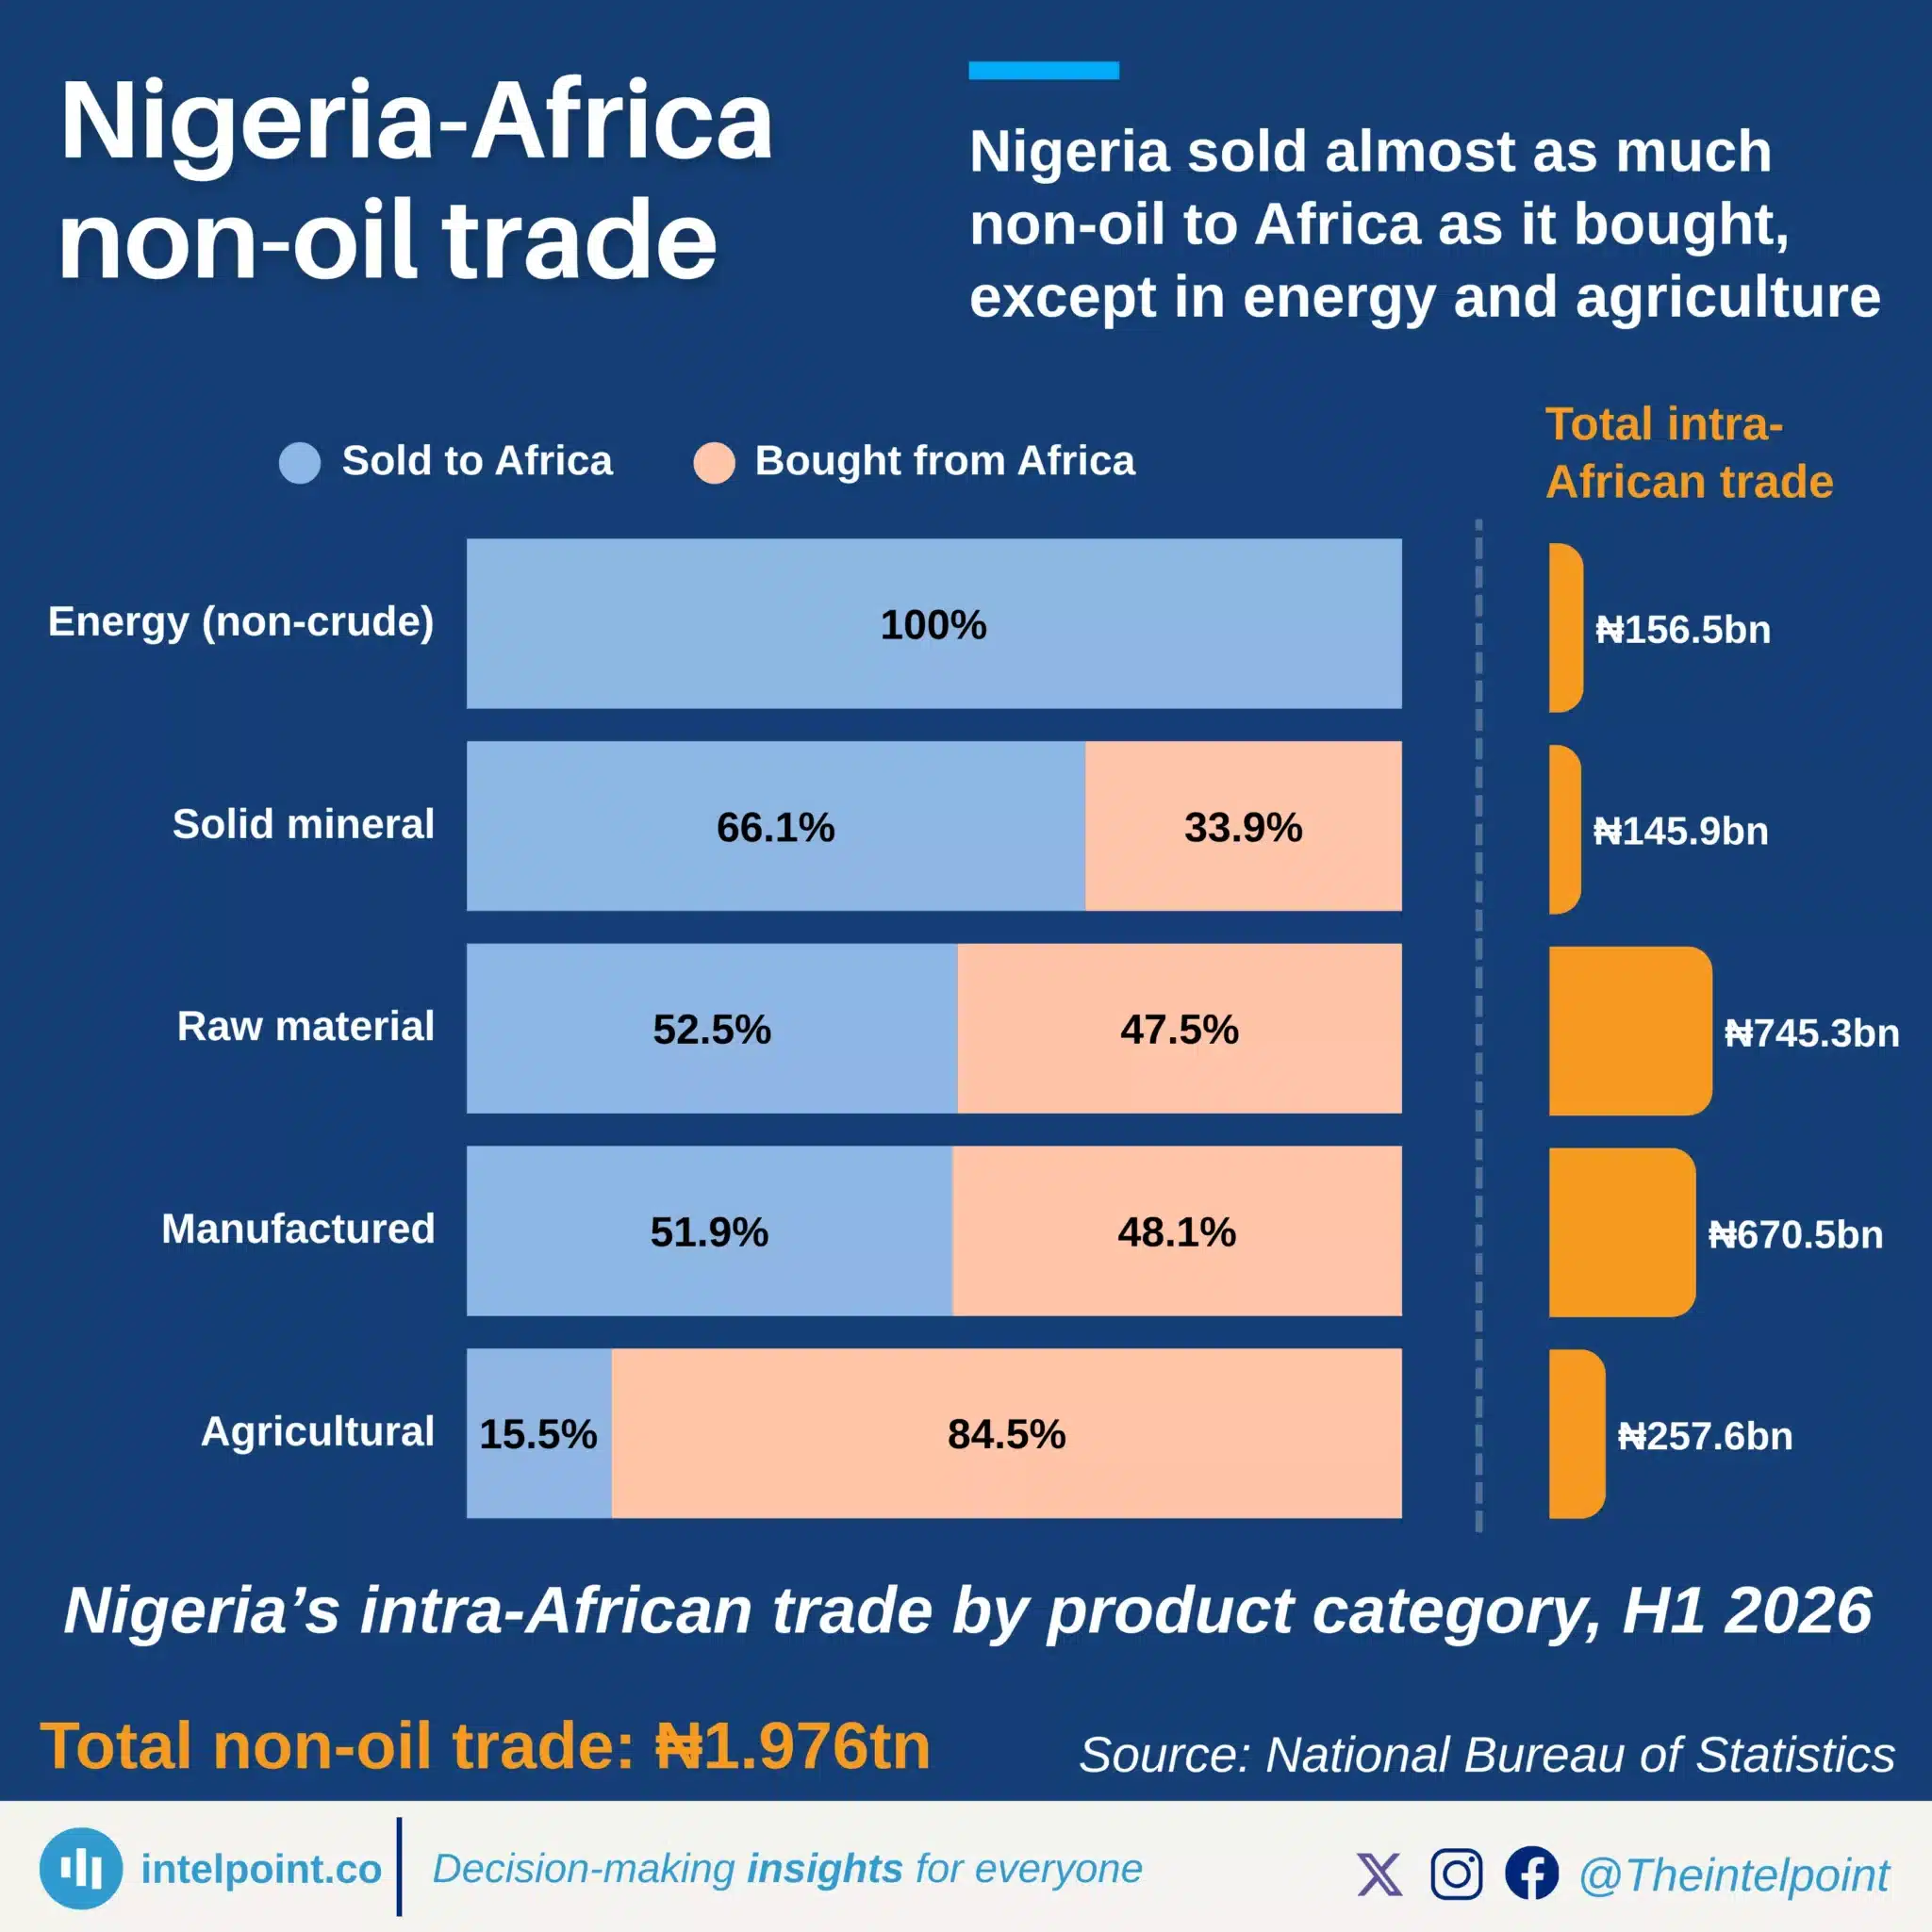
Nigeria sold almost as much non-oil to Africa as it bought, except in energy and agriculture
  • Nigeria’s non-oil trade with Africa was nearly balanced, with an ₦88bn surplus on almost ₦2tn of trade in H1 2026.
  • Energy trade was entirely export-led, with Nigeria selling ₦156.5bn and recording no imports.
  • Solid minerals also leaned towards exports, with sales making up 66.1% of category trade.
  • Agriculture ran a large deficit, as imports accounted for 84.5% of trade and exceeded exports by ₦178bn.
  • Nigeria’s agricultural trade deficit widened sharply, from ₦59bn in Q1 to ₦119bn in Q2.

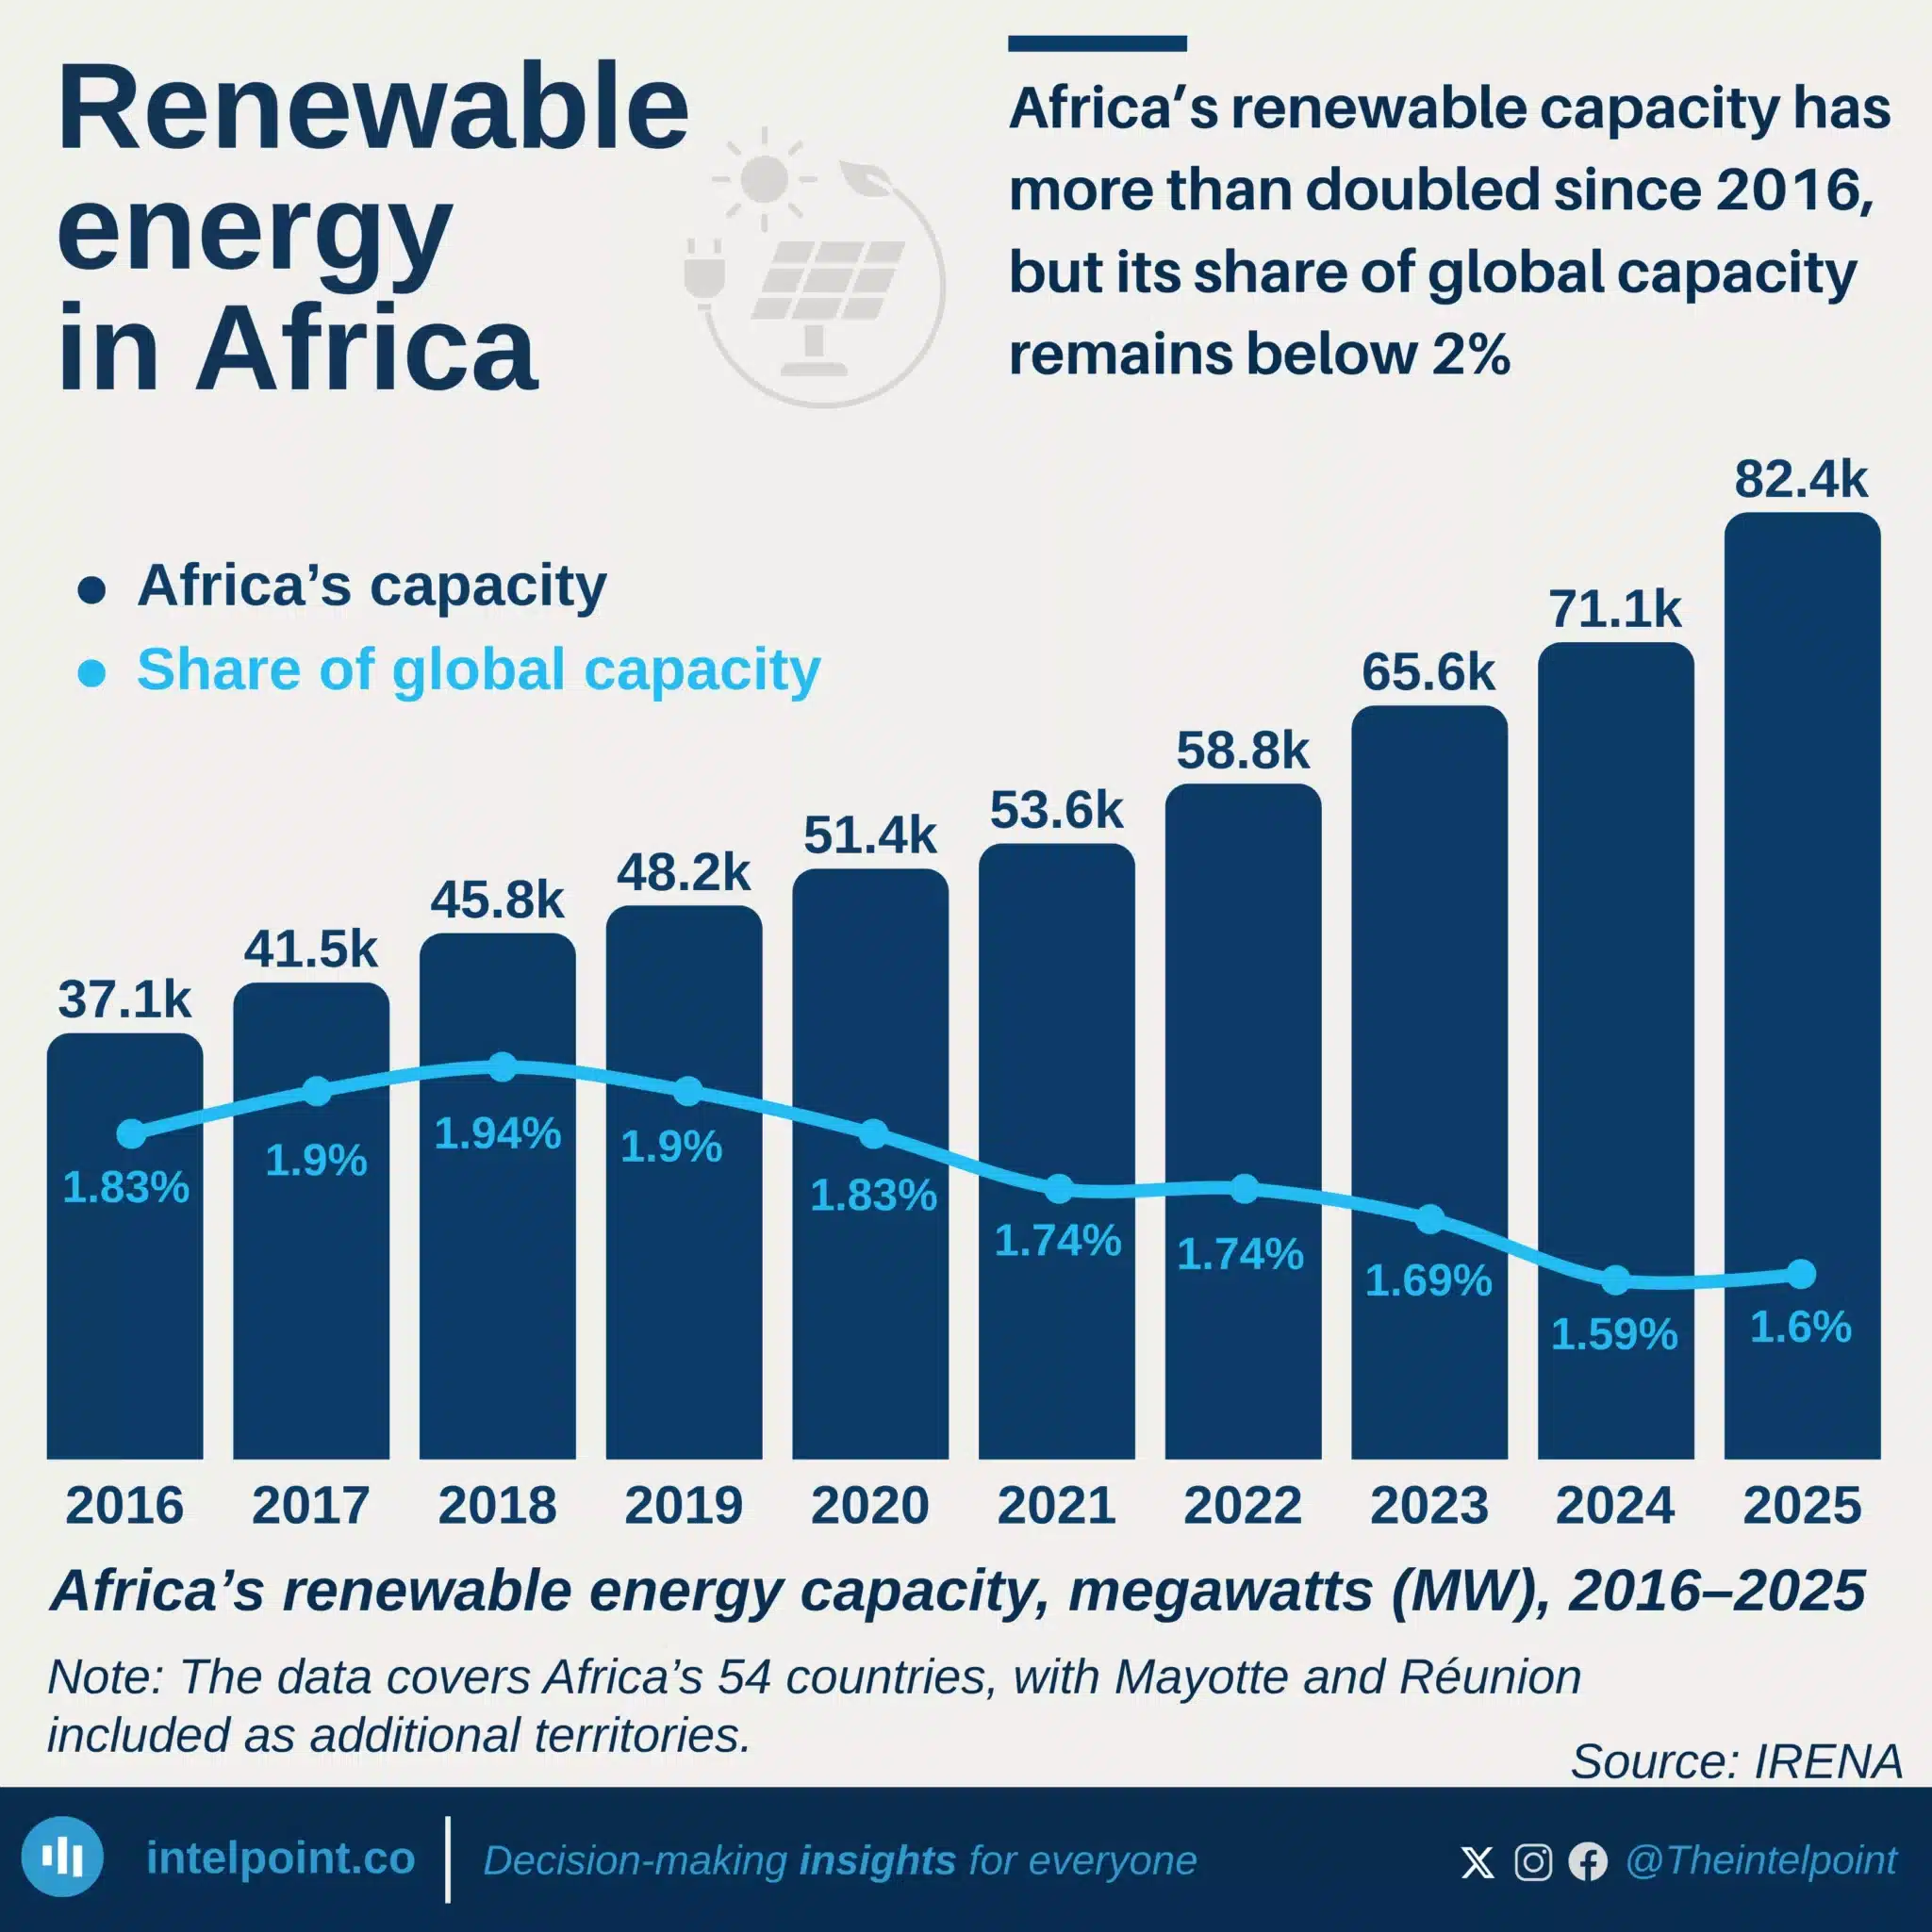
Africa’s renewable capacity has more than doubled since 2016, but its share of global capacity remains below 2%
  • About 600 million Africans still lack access to electricity.
  • Africa has 20% of the world's population but receives less than 3% of global energy investment.
  • South Africa added the most renewable capacity from 2016–2025, followed by Ethiopia, Egypt, Morocco and Tanzania.
  • Africa's renewable capacity is growing, but its share of global capacity remains small.

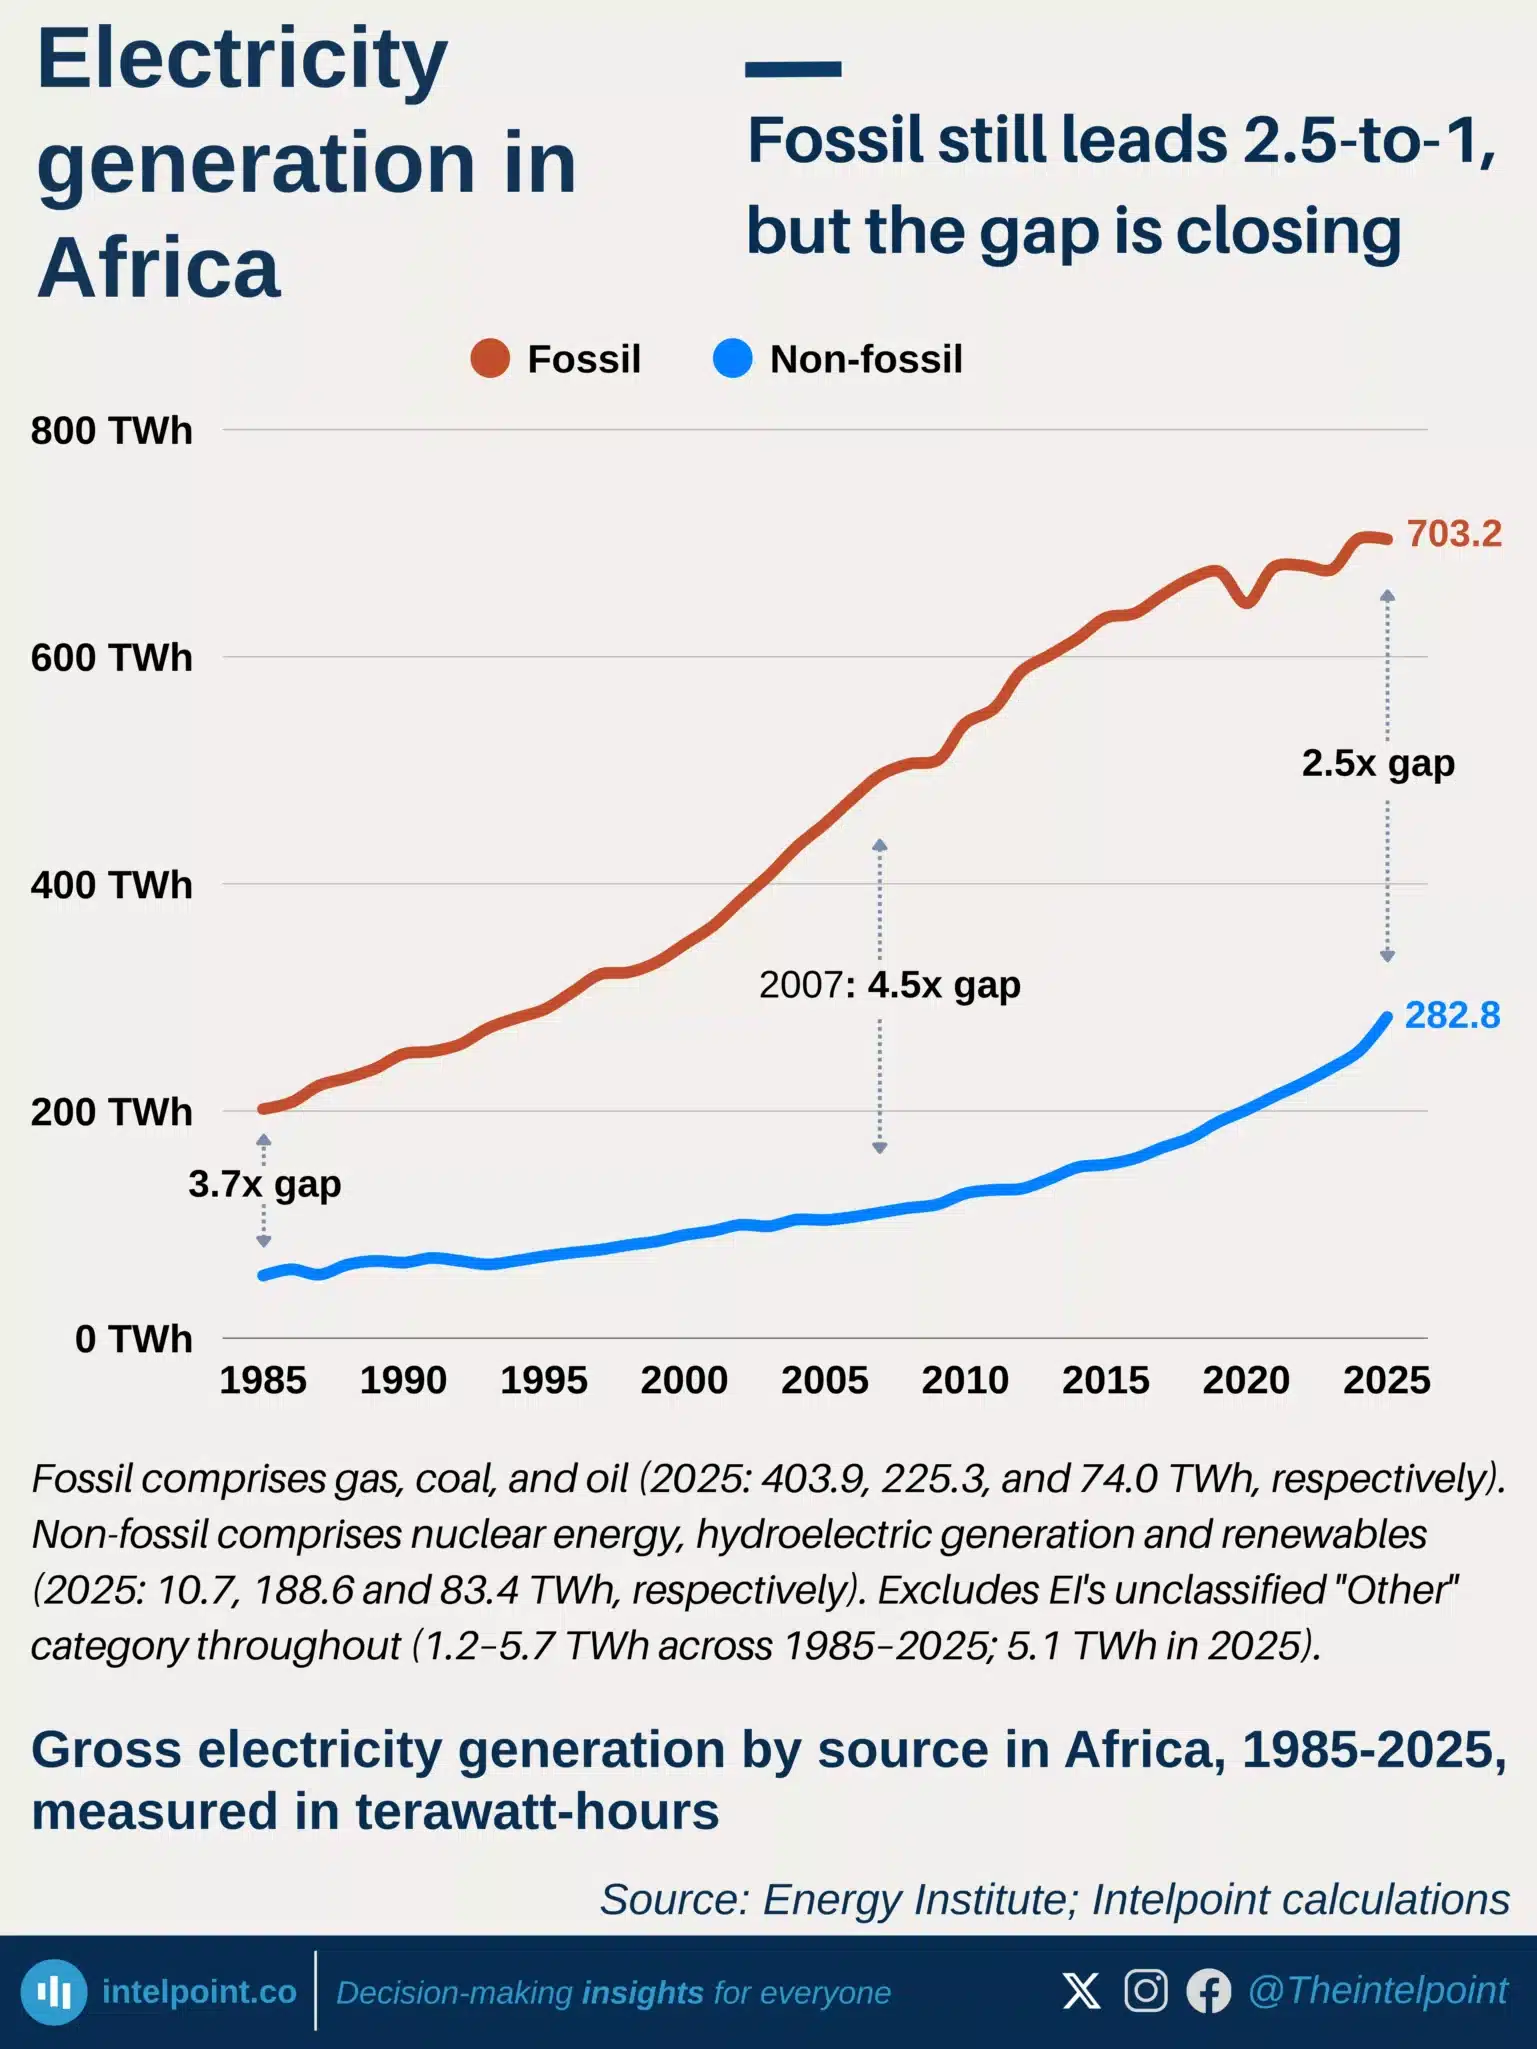
Electricity generation in Africa: fossil still leads 2.5-to-1, but the gap is closing
  • Fossil fuels still generate 2.5x more electricity than non-fossil sources, though the gap has narrowed from a 2007 peak of 4.5x.
  • South Africa and Egypt together account for all of Africa's nuclear power and 59% of its non-hydro renewables.
  • Hydropower, the largest non-fossil source at 188.6 TWh, tells a different geographic story, with 91% generated outside South Africa and Egypt, mainly in Eastern, Middle, and Western Africa.
  • Gas still leads at 403.9 TWh, but its growth slowed to 0.8% in 2025 versus 11.9% growth for non-fossil sources.

POPULAR TOPICS
SIGN UP TO OUR NEWSLETTER
Get periodic updates about the African startup space, access to our reports, among others.
Subscribe Here
Subscription Form

A product of Techpoint Africa. All rights reserved